Quick answer
A home-loan pre-approval is a lender’s preliminary view of how much it may lend based mainly on your current financial profile. It helps set a search range, but it is not a final sanction, does not approve a particular property, and should not replace your own affordability limit or legal review.
House hunting before understanding finance can waste time and create pressure to accept an unsuitable loan. Pre-approval can organise the process by showing how a lender currently views income, debt, credit history, age, and repayment capacity. Used correctly, it narrows the search and highlights documentation issues early.
Used carelessly, the same figure becomes a spending target. Lenders assess whether a loan may fit their policy; they do not know every household goal, future expense, or risk. This guide explains what pre-approval means, what can change, and how to use it without overstretching.
What a pre-approval usually evaluates
The lender may examine identity, income, employment or business stability, bank statements, tax records, existing obligations, repayment history, credit information, age, and requested tenure. Policies vary, and the lender may ask for additional evidence or verify data later.
The output may state an indicative amount, rate range, tenure, conditions, and validity period. Read whether fees were charged and whether a credit enquiry was made. An indicative offer can expire or change when income, debt, credit, rates, or lender policy changes.
Why eligibility is not affordability
Eligibility is the lender’s maximum under its rules; affordability is the payment your household can carry while saving and living normally. Build affordability after essentials, insurance, dependants, education, transport, maintenance, retirement saving, and variable income.
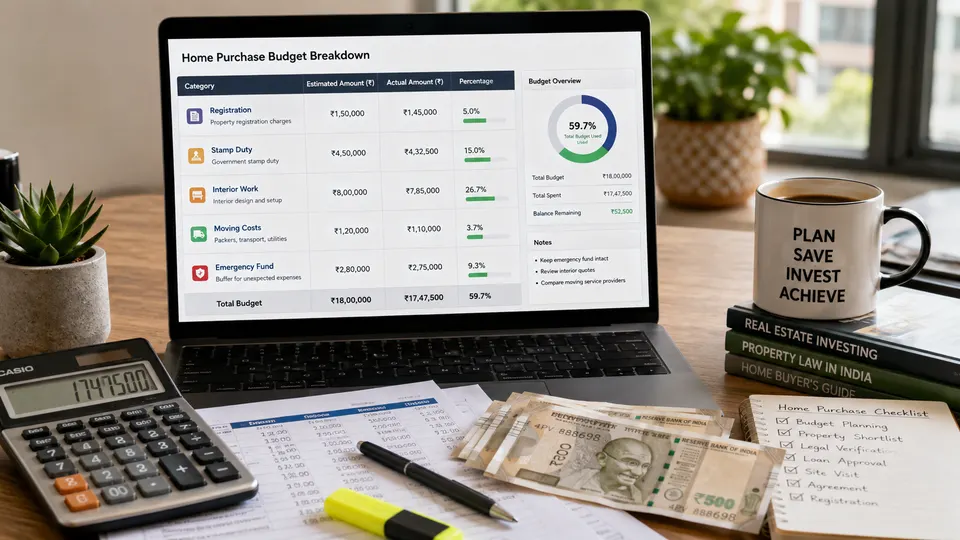
Stress-test EMI at a higher rate and include the complete ownership cost. Keep emergency reserves after the down payment. If the pre-approved maximum would eliminate reserves or require future bonuses, lower the search ceiling.
How it improves a property search
Pre-approval can reveal the likely down payment and help compare ready, resale, and under-construction cash flow. It can focus conversations with sellers and reduce the chance of agreeing to a payment schedule before finance is considered.
It also provides time to correct document mismatches, reduce expensive debt, organise tax records, or build the down payment. Do not make repeated applications merely to collect maximum figures; compare lenders thoughtfully and understand credit-enquiry implications.
What remains before final sanction
After selecting a property, the lender evaluates legal and technical documents, valuation, loan-to-value, project or seller information, and specific transaction terms. The approved amount may be lower than pre-approval if valuation is lower than price or the property does not satisfy policy.
The bank’s review protects its lending decision, not every buyer interest. Continue independent title, agreement, project, and inspection work. Do not make a non-refundable commitment merely because an eligibility message was received.
Compare loan offers beyond the rate
Compare benchmark, spread, fixed or floating period, reset frequency, tenure, processing, legal and valuation fees, insurance, prepayment, conversion charges, disbursement, and service. Ask for a written repayment illustration and total cost under more than one rate scenario.
A long tenure lowers initial EMI but may greatly increase interest. Choose a structure compatible with stable cash flow and planned prepayments without assuming future income growth. Review whether bundled insurance is optional and compare coverage independently.
Protect approval until disbursement
Avoid new loans, large credit-card balances, missed payments, or unexplained bank transfers during processing. Inform the lender about employment or income changes. Keep margin money and statutory charges available through traceable sources.
Coordinate agreement milestones, seller demands, and lender conditions. Know what documents trigger each disbursement and who confirms construction progress. Preserve sanction, key facts, schedules, receipts, and correspondence in one file.
Prepare for a valuation shortfall
A lender may value the selected property below the agreed price or exclude charges that the buyer assumed would be financed. The loan can then be smaller even when income eligibility is unchanged. Before offering, ask how the lender calculates loan-to-value, which cost components are excluded, and how much additional cash would be needed under a conservative valuation.
Do not solve the gap by emptying the emergency reserve or taking expensive unsecured debt without recalculating affordability. The safer choices may be renegotiating the price, selecting another property, increasing the planned down payment gradually, or using a different lender after comparing complete terms. Put a finance condition and a clear refund mechanism into the offer wherever the transaction permits.
Keep the valuation separate from legal approval. A bank may accept value but reject documents, or accept documents while valuing conservatively. Both reviews are lender decisions; neither replaces the buyer's independent lawyer, inspection, or all-in budget.
Pre-approval checklist
- Calculate your own safe EMI before applying.
- Organise income, tax, bank, identity, and debt records.
- Read amount, validity, assumptions, fees, and conditions.
- Keep down payment, transaction costs, and reserves separate.
- Compare complete written loan terms.
- Make offers conditional on property and final finance review.
- Avoid financial changes before sanction and disbursement.
Frequently asked questions
Does pre-approval guarantee a home loan?
No. Final sanction depends on updated borrower information, the specific property, valuation, legal and technical acceptance, documentation, and lender policy.
Should I search up to the full approved amount?
Not automatically. Use your own all-in budget and safe EMI, which may be lower after household goals, ownership costs, and reserves are included.
Can I negotiate better with pre-approval?
It can demonstrate preparation, but never waive document, inspection, valuation, or refund protections merely to appear like a faster buyer.
Final takeaway
Pre-approval is a planning tool, not permission to spend the maximum. Use it to set a realistic search, compare lenders, and prepare documents—then complete independent property checks and wait for final sanction before relying on the funds.
Important: Loan products and eligibility policies vary and change. Obtain current written terms from regulated lenders and personalised financial advice where needed.