Quick answer
A sustainable property investment uses conservative rent and appreciation assumptions, manageable debt, complete cost, emergency and vacancy reserves, legal clarity, diversification, and a holding period long enough to absorb transaction costs. If the household needs perfect occupancy or rapid resale to meet payments, the investment is overstretched.
Property is attractive because it is tangible and finance can magnify ownership. The same leverage also turns a slow market, vacancy, repair, or income interruption into a monthly obligation. Long-term success therefore begins with survival capacity, not a projected return.
This guide helps households decide how much property risk they can carry. It does not assume that prices always rise and does not compare property with financial products without accounting for liquidity, concentration, and work.
Define the investment job
Choose whether the property is intended for rent, future self-use, capital preservation, business use, or development. Each goal favours different locations and assets. A future home may justify lower yield; a rental purchase needs tenant evidence; a plot needs a long horizon and provides no regular income.
Write the target holding period, expected cash flow, maximum management work, and conditions for selling. Avoid buying because the market feels active without knowing how the asset fits the rest of the household plan.
Use complete cost and conservative income
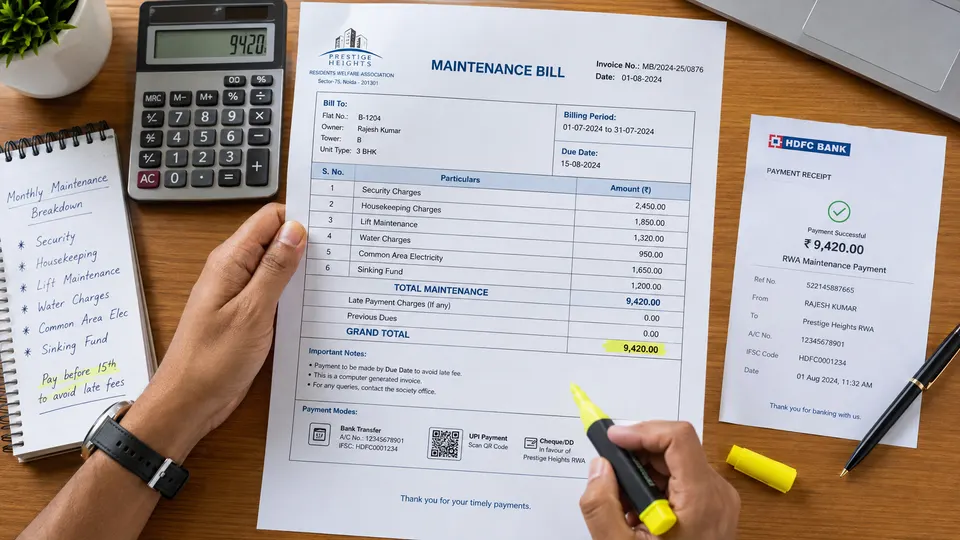
Add purchase, duties, registration, brokerage, legal and technical work, loan fees, furnishing, repair, taxes, maintenance, insurance, management, and sale costs. Calculate return on the full capital committed, not only the down payment unless leverage risk is shown separately.
Use achieved comparable rent, allow vacancy, and deduct recurring costs. Model no appreciation in the base safety case. Appreciation may improve the result, but it should not be required to meet EMI or recover a poor entry price.
Set leverage from downside cash flow
Test higher interest, lower rent, several vacant months, a major repair, and temporary household income loss together. If reserves disappear quickly, reduce the loan or purchase price. A bank’s eligibility is not a risk recommendation.
Avoid using every liquid asset for the down payment. Keep household emergency funds and property reserves in accessible form. Plan insurance and nomination or estate documentation appropriate to the family.
Protect against concentration
One apartment can represent a large share of net worth, one tenant all property income, and one micro-market all geographic exposure. Consider the household’s job location, existing home, business, and other assets before adding more risk to the same area.
Diversification does not require owning many properties. It may mean keeping sufficient liquid and marketable assets rather than buying a second unit. Compare direct ownership with regulated alternatives using professional advice and your need for control.
Plan operations and capital expenditure
Budget recurring painting, waterproofing, appliances, brokerage, vacancy, society assessments, tax, and tenant turnover. Older buildings and furnished rentals need replacement schedules. Good management preserves value but costs time or fees.
Maintain leases, inventories, inspections, receipts, warranties, and communication. Choose a local manager if remote. Deferred repair can turn a small problem into vacancy and a larger capital expense.
Design an exit before entry
Identify the likely resale buyer, affordable price band, documentation needed, and realistic marketing time. Specialised, high-ticket, or unclear properties can be illiquid. Model brokerage, tax advice, loan release, and a negotiated sale price.
Review the investment annually using actual rent, expenses, vacancy, condition, debt, and market evidence. Do not sell solely because a portal estimate moves, but do not hold indefinitely when the original demand case has broken.
Run an annual investment review
Once a year, compare actual rent, vacancy, maintenance, repairs, taxes, loan interest, and cash invested with the original model. Note changes in occupancy, competing supply, tenant profile, building condition, connectivity, and project governance. Separate temporary noise from a lasting change in the reason the property was bought.
Update three choices: hold as-is, improve operations, or prepare an exit. Operational improvement might mean preventive repair, better tenant screening, realistic rent, or formalising records. An exit review should include brokerage, tax advice, loan closure, document readiness, and realistic selling time. Do not hold merely because the price once paid feels important; judge the asset against current goals and credible alternatives.
Also review concentration. A household with most savings tied to one illiquid property needs more liquidity and insurance than a buyer with a diversified portfolio. The annual review is not an invitation to trade frequently. It is a check that the original thesis, cash flow, and risk remain acceptable.
Long-term investment safety checklist
- Purpose, holding period, and exit condition defined.
- Complete acquisition and sale cost modelled.
- Rent reduced for vacancy and owner expenses.
- Debt survives higher rates and income interruption.
- Household and property reserves remain intact.
- Concentration and liquidity reviewed.
- Annual operations and performance review scheduled.
Frequently asked questions
How much emergency reserve should an investor hold?
The right amount depends on EMI, household stability, vacancy, condition, and dependants. Model combined adverse events and keep enough accessible funds to avoid a forced sale.
Should appreciation be included?
Use scenarios rather than a guarantee. A safety case with no appreciation tests whether rent, cost, and holding capacity are defensible.
Is a second property diversification?
Not necessarily. Two properties can concentrate wealth in the same asset class, city, financing risk, and economic driver.
Final takeaway
Long-term investing rewards the ability to hold a sound asset through ordinary setbacks. Buy below your maximum capacity, verify demand and documents, reserve cash for operations, and let appreciation remain an uncertain upside rather than the plan’s foundation.
Important: Property investing involves loss, vacancy, financing, legal, and liquidity risk. Obtain advice suited to your finances.