Quick answer
Rental demand should be measured through tenant enquiries, achieved rents, vacancy time, competing supply, and net cash flow—not through a broker’s promised yield. Study the likely tenant, visit competing properties, verify actual lease evidence where available, and stress-test the investment before buying.
A property can be attractive to buyers and still be difficult to rent. Investment decisions fail when the purchaser begins with the unit and only later asks who will occupy it. A stronger process starts with the tenant: what brings people to the area, what monthly payment can they sustain, which layout they prefer, and how many similar homes compete for their attention?
Rental demand is local and segment-specific. A furnished studio near an employment cluster, a family apartment near schools, and a large premium home may behave differently in the same pin code. This guide explains how to collect evidence, calculate net yield, and recognise warning signs before your capital is locked into the wrong product.
Define the tenant before studying the property
Write a realistic tenant profile: household size, occupation, commute, budget, lease duration, furnishing needs, parking, pet policy, and preferred move-in date. Then ask whether the proposed unit solves that tenant’s daily problem. A large clubhouse does not compensate for an unreliable commute, and an extra room may not justify higher rent if most local demand comes from single professionals.
Use more than one demand driver. Employment, education, healthcare, industrial activity, and established family neighbourhoods can each support rentals, but dependence on one employer or college creates concentration risk. Examine what would happen if that institution relocates, work-from-home patterns change, or a large amount of competing inventory is completed nearby.
Measure demand with observable evidence
Track comparable listings for several weeks. Record date first seen, asking rent, furnishing, floor, area, maintenance treatment, and whether the listing disappears, is reduced, or repeatedly reposted. A long list of advertisements is not proof of demand; it may indicate high vacancy. Speak separately with property managers, residents, tenants, and more than one broker to reduce sales bias.
Ask for achieved rent rather than headline rent. Where privacy and access permit, review anonymised lease evidence or society move-in records. Visit on weekday evenings to see occupancy signs and talk with security or facility teams about move-in frequency without requesting private tenant data. A healthy market usually shows reasonable enquiry, realistic negotiation, and turnover that matches the target segment.
- Median time on market for genuinely comparable units.
- Difference between asking rent and signed rent.
- Seasonality around school, university, or corporate joining cycles.
- Number of vacant units in the same tower or society.
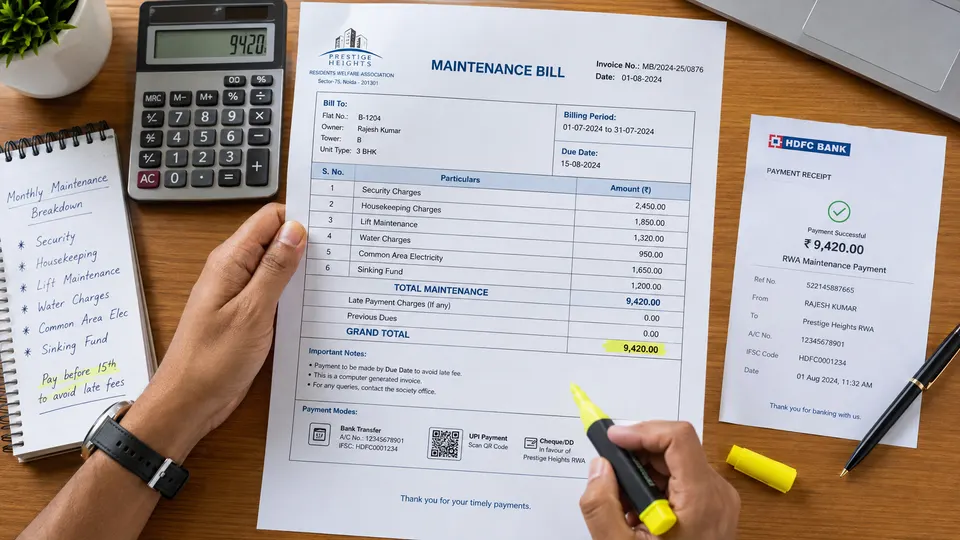
- Tenant-paid versus owner-paid maintenance and utilities.
Calculate net rental yield, not brochure yield
Gross yield divides annual rent by purchase price, but it ignores costs. Start with the complete acquisition amount: price, duties, registration, brokerage, loan charges, furnishing, repairs, parking, and deposits that are not recoverable. Then estimate collected rent after vacancy rather than multiplying the best advertised monthly figure by twelve.
From collected rent, subtract owner-paid maintenance, property tax, insurance, periodic painting, appliance replacement, brokerage on tenant changes, legal or documentation expenses, and an allowance for unexpected repairs. Interest and principal affect cash flow differently, so maintain both a property-level return view and a household cash-flow view. A deal that looks profitable before vacancy may become negative after one empty quarter.
Study competing supply and future deliveries
Inspect the surrounding pipeline. New towers can expand the tenant pool, but they can also release hundreds of similar units at once. Under-construction supply, unsold builder inventory, investor-owned flats, and conversion of owner-occupied homes to rentals all influence future negotiation power. Compare unit sizes and furnishing packages because tenants often search by monthly outflow, not by project brand.
Also examine replacement competition. A tenant may choose a nearby co-living space, independent floor, older apartment, or a location one metro stop away. Your demand analysis should therefore extend beyond the same society. Map alternatives within the tenant’s commute and budget, then identify a durable reason your unit would win without requiring the lowest rent.
Assess operational and tenant-management realities
Rental property is an operating asset. Clarify society rules for tenants, move-in charges, police verification, pets, bachelor occupancy, commercial activity, and short stays. Restrictive rules may reduce the target market. Check whether maintenance complaints are resolved promptly, lifts and backup work reliably, and water supply is stable; recurring service failures create turnover even when the location is strong.
Decide who will market, inspect, document, and maintain the property if you live elsewhere. Price property-management fees and response time into the plan. Keep an inventory, condition report, deposit record, and written process for repairs. Good operations protect rent and reduce disputes; they should not be treated as free work.
Stress-test the investment before committing
Model a base case, a cautious case, and a difficult case. In the cautious case, reduce rent, add vacancy, increase maintenance, and assume a repair. In the difficult case, include several months without rent and a slower sale. Test whether your emergency reserve and household income can carry the loan and expenses without forcing a distressed exit.
Do not use hoped-for appreciation to repair weak current economics. Capital growth is uncertain and transaction costs make short holding periods expensive. A resilient rental purchase has a clear tenant, sensible total cost, manageable leverage, legal clarity, and enough cash reserve to survive ordinary vacancy and repairs.
Rental-demand research checklist
- Define one primary and one secondary tenant profile.
- Track at least ten comparable rentals over several weeks.
- Record achieved rent, vacancy time, and negotiation where evidence is available.
- Calculate net yield using the complete acquisition cost.
- Review society tenancy rules and competing upcoming supply.
- Budget for vacancy, repairs, brokerage, and management.
- Test cash flow under lower rent and higher interest or expenses.
Frequently asked questions
What is a good rental yield?
There is no universal number. Compare net yields among similar assets after all recurring costs, vacancy, and acquisition expenses, then judge the result against risk, liquidity, financing, and alternative investments. A higher quoted yield may compensate for weaker resale demand or greater management work.
How long should I study listings?
Several weeks is more informative than a one-day snapshot, and longer observation is valuable where demand is seasonal. The aim is to see listings appear, change price, and close rather than count advertisements at one moment.
Does proximity to an office guarantee tenants?
No. Commute convenience helps, but rent, unit condition, transport, neighbourhood services, employer concentration, and competing supply also matter. Validate demand with actual comparable leases and tenant conversations.
Final takeaway
Assessing rental demand is an evidence exercise. Begin with the tenant, observe how comparable homes perform, calculate net income honestly, and test a downside case. This work cannot guarantee returns, but it can prevent a persuasive sales story from becoming an expensive vacancy problem.
Important: Rental income, vacancy, expenses, financing costs, and property values can change. Obtain legal, tax, and financial advice suited to your circumstances.